Before You Read On:
The income limits are low (see the table below), and dependents are not eligible. That means young workers supported by their parents and full-time students under age 24 won’t qualify. For those who do qualify, though, the government will add up to $1,000 a year to their retirement savings.
Good news for savers: starting in 2027, a new federal program will add free money to the retirement accounts of millions of lower- and moderate-income workers. The income limits are low (see the table below), and dependents are not eligible. That includes many young workers still claimed on a parent’s return. Full-time students aren’t eligible either. For those who do qualify, though, the government will add up to $1,000 a year to their retirement savings.
The Treasury and the IRS recently released Notice 2026-48, the first detailed guidance on how it will work. This is guidance, not final rules. Those are still being worked out, so details may change. Here’s what we know so far, whether you’re an employee or an employer.
The Basics
The Saver’s Match replaces the Saver’s Credit, a tax credit for lower-income savers. The government will match 50% of up to $2,000 in annual contributions, for a maximum of $1,000, deposited directly into a retirement account. Matches are based on 2027 contributions, and payments are expected to begin in 2028.
For Employees
Are you eligible? For 2027, it depends on your filing status and modified adjusted gross income (MAGI), which for most people is close to the income on your tax return. Below the first amount, you get the full match. Between the two amounts, the match shrinks gradually until it reaches zero.
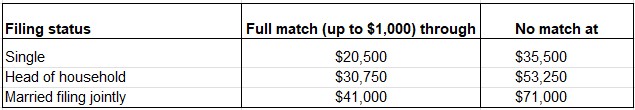
Dependents and full-time students are not eligible. These limits will be adjusted for inflation after 2027.
How will you claim it? You’ll file your tax return along with a separate Form 8880-A (still pending), and the IRS will calculate your match. Unlike the old credit, the match is deposited into your account even if you owe no income tax.
Next steps for you:
• Estimate whether your 2027 income will land within the limits.
• Plan to contribute the full $2,000 to capture the maximum match.
• Ask your plan or IRA provider whether they will accept Saver’s Match deposits.
For Employers and Plan Sponsors
Participating is your call. Plans are encouraged, but not required, to accept the Saver’s Match, and the notice lets a plan add or drop the feature freely. If you opt in, you’ll need to decide how the money arrives. The notice describes three possible paths:
- Automatic match path. Your recordkeeper (the company that administers your plan’s accounts and tracks each employee’s contributions and balances) shares plan and participant data with the Treasury and the IRS. The match is deposited directly into employees’ accounts.
- Registration path. Your plan registers with the Treasury. The match travels through a government conduit IRA, a temporary account used only to pass the money along, and is immediately rolled into your plan.
- Rollover path. The employee tells the IRS where to send the match. It passes through a temporary conduit IRA and is rolled over like any other rollover.
Next steps for you:
- Ask your recordkeeper which of these paths they plan to support.
- Decide whether your plan will accept Saver’s Match deposits.
- Let eligible employees know about the program. Many won’t have heard of it yet.
What happens next
The comment period closed October 5, 2026, and proposed regulations will follow. We’ll keep sharing more information as the program evolves.