Trump Accounts are a new savings vehicle for children, and many clients are asking how they fit alongside tools like 529 plans, Roth IRAs and custodial accounts. The short answer is that they add an option rather than replace anything.
Keep in mind
Before we get into the details, two points are worth knowing up front:
- Limited flexibility: Trump Account funds are locked up until the child is nearly 18, so this shouldn’t replace emergency savings.
- More guidance is coming: The current rules are only proposed, and the IRS has yet to address distributions, reporting and employer programs. We’ll keep you updated as details are finalized.
With that in mind, here is how Trump Accounts work.
The basics
A Trump Account is a tax-advantaged account for a child under 18 with a Social Security number. It works like a traditional IRA for a minor: the child owns it, and a parent or guardian manages it. Unlike a 529 plan, it isn’t limited to education costs.
The $1,000 federal seed
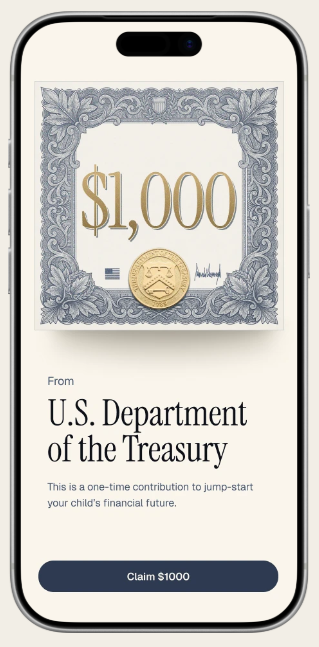
Children born between January 1, 2025 and December 31, 2028, who are US citizens with a Social Security number, may receive a one-time $1,000 deposit from the Treasury. It isn’t automatic: a parent or guardian must claim their child’s account through the Treasury’s Trump Accounts app.
Who can contribute, and how much?
- Family and friends: Up to $5,000 per child per year in total, indexed for inflation after 2027. The $1,000 federal seed money doesn’t count toward the cap.
- Employers: Up to $2,500 per employee per year, which counts toward the $5,000 limit. Employers can deduct the contribution, and the employee isn’t taxed on it.
- Charities and governments: Eligible nonprofits and governments can fund equal deposits for an entire group of children, such as all children in a region. These gifts don’t count toward the $5,000 limit, and they can’t be directed to an individual child.
Taxes and access
Your own contributions are made with after-tax dollars and aren’t deductible. Earnings grow tax-deferred. When money is withdrawn, employer contributions, the federal seed money and earnings are taxed as ordinary income. Your own contributions were made with after-tax dollars, so that portion generally isn’t taxed again.
Funds are invested in a limited menu of low-cost index funds. Withdrawals are generally not allowed before the year the child turns 18, with narrow exceptions. After that, the account becomes a regular IRA, subject to ordinary income tax and early-withdrawal penalties before age 59½.
How it fits with other tools
- 529 plans remain the best choice for education savings, and many families will use both.
- Custodial accounts can create annual taxes and financial aid issues that Trump Accounts largely avoid.
- Roth IRAs require earned income. A Trump Account can bridge the gap until a child starts working.
Grandparents who already fund 529s may also like this as another long-term gifting option. Business owners should talk to us about employer contributions, which come with payroll and reporting considerations.
How we can help
We can help you determine how a Trump Account fits into your broader savings and gifting strategies. Contact your accountant if you’d like to discuss this further.
This post is general information, not tax, legal or investment advice. Rules may change as additional guidance is issued.